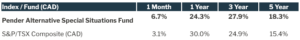
The Pender Alternative Special Situations Fund returned 6.7%1 in August, compared to the S&P/TSX Composite, which rose 3.1% during the month.
Fund Specific Updates
Following a more challenging July, August marked a return to positive territory for the themes we most closely track, as well as several event-driven holdings contributing strongly to performance. In a sharp reversal from last month, two of our key thematics, space/defence and critical minerals, outperformed. Telesat Corp. (TSAT), a position we added to last month on share price weakness, and Blue Moon Metals (MOON) were top performers.
More broadly within Materials, the Fund experienced strong performance across its sector exposure. White Gold Corp, NexGen Energy, IsoEnergy and Montage Gold were among the largest contributors during the month. It is encouraging to see that investor sentiment has turned around following months of volatility over shorter periods.
We continue to believe well-capitalized businesses with high-quality assets, strategic processing capabilities and exposure to supply-constrained minerals are positioned to benefit as these structural trends translate into tighter markets and improved pricing. Uranium was a notable contributor during August as the spot U₃O₈ price continued to strengthen, while the long-term price also saw a meaningful increase. We believe the move reflected an increasingly constructive fundamental backdrop, with growing uncovered utility requirements and continued uncertainty around the availability and timing of future supply. Improving uranium prices and sector sentiment provided a meaningful tailwind to our holdings in NexGen Energy, IsoEnergy and Uranium Energy Corp., while our position in the Sprott Physical Uranium Trust provided more direct exposure to the commodity. We continue to believe that the combination of increasing nuclear power demand, a developing utility contracting cycle and constrained new mine supply provides a favourable multi-year backdrop for uranium prices and high-quality uranium equities.
Most notably, in August we saw major positive developments for two of our Canadian defence and space holdings, Telesat and MDA Space. Telesat signed the largest contract in its history, a $2.3 billion agreement with the Government of Canada to provide secure military connectivity in the Arctic for the Canadian Armed Forces. The agreement will also expand the fully funded Telesat Lightspeed constellation from 156 to 225, materially increasing its capacity and commercial potential. For Telesat, this was a major catalyst and in our view the contract materially de-risking the funding and commercialization of Lightspeed and positioning Telesat as a key provider of secure connectivity to users globally.
An equally important and potentially underappreciated part of this announcement is MDA's selection as prime contractor for the proposed Ultra-High Frequency and X-band medium-Earth-orbit constellation. MDA will be responsible for end-to-end mission delivery, with Telesat serving as a key subcontractor and systems integrator. Negotiations are underway, with contract details to be disclosed once finalized. While the market reaction has been significant, we still believe both companies remain attractively valued. We added to our position in MDA during the month, as we believe the company is well positioned to win several new contracts. MDA recently announced two acquisitions that give it footholds in the US and European space markets: Blue Canyon Technologies (BCT), a US-based spacecraft and satellite component manufacturer, and a 70% stake in Collecte Localisation Satellites (CLS), a European Earth-observation and geointelligence business. Together, the deals broaden MDA's addressable customer base and competitive positioning and are expected to meaningfully expand its recurring revenue base. With its sales pipeline continuing to build, we see potential for further contract wins ahead.
For the second straight month, a notable area of strength was our equity position in McDermott International Ltd. (MCDIF), which was the top contributor for the month as the market began pricing in some of the value we had been underwriting ahead of it. We continue to view McDermott as an attractive reorganization equity opportunity, one where Pender's fixed income team's expertise proved valuable, particularly in analyzing the company's restructuring, capital structure, and the value of the securities that emerged from that process. The rights issue executed in August was an important catalyst as it is expected to strengthen McDermott's balance sheet, improve its financial flexibility, and help create a clearer path toward a potential liquidity event. As the balance sheet strengthens and that path becomes clearer, we believe the current valuation discount to narrow and the underlying value of the business to be realized.
Portfolio Updates
Volatility in markets continued into August. Beneath relatively stable headline index levels, we continued to see meaningful dispersion across sectors and individual names, a dynamic that has historically preceded periods of broader volatility. Against this combination of unresolved risks and a market that has, in our view, priced in a fair amount of good news, we believe a measured and defensively postured approach remains warranted. Against this backdrop, we positioned the portfolio around three priorities:
- Preserving optionality: Against this backdrop, we continue to maintain a defensive posture with a cash position. This was not intended as a broad market call; rather, the additional liquidity provides the Fund with greater flexibility to capitalize on forced selling and company-specific dislocations without having to reduce core positions at an inopportune time.
- Increasing exposure to hard catalysts: We increased exposure to investments with identifiable, time-bound catalysts—such as contract awards, recapitalizations and strategic transactions—where returns are more dependent on company-specific developments than on broad market direction or multiple expansion. We believe these opportunities can provide a more differentiated source of return when market beta becomes less reliable.
- Maintaining downside protection: We maintained portfolio hedges to moderate downside participation while preserving exposure to our highest-conviction investments. With headline index stability masking meaningful dispersion and several macroeconomic and geopolitical risks still unresolved, we believe maintaining protection is prudent and should leave the Fund well positioned to deploy capital if volatility creates more attractive opportunities.
Amar Pandya, CFA
Portfolio Manager
September 22, 2026
1 All Pender performance data points are for Class F of the Fund. Other classes are available. Fees and performance may differ in those other classes. Standard Performance Information for the Fund may be found here: https://penderfund.com/fund/pender-alternative-special-situations-fund/
Standard Performance Information for Pender’s Liquid Alternative Funds may be found here: https://www.penderfund.com
This commentary is subject to the Disclaimer found here: https://www.penderfund.com/disclaimer/
© Copyright PenderFund Capital Management Ltd. All rights reserved. September 2026.