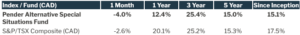
The Pender Alternative Special Situations Fund returned -4.0%1 in September, compared to the S&P/TSX Composite, which fell -2.6% during the month.
September was a challenging month for equities, as continued inflation pushed central banks to begin tightening. With price pressures still running above target, both the US Federal Reserve and the European Central Bank raised interest rates during the month, while the Bank of Canada held its policy rate steady at 2.25%. Bond yields moved higher in response, and the pressure fell hardest on the more rate-sensitive corners of the market, most notably small caps bore the brunt of the selling and we saw the Russell 2000 decline more than 5%.
Energy remained a key source of the inflationary pressure. Ongoing geopolitical tensions in the Middle East kept crude oil, gasoline and diesel prices elevated, leaving investors to weigh the knock-on effects for interest rates and economic growth. Closer to home, the Canada–US trade dispute escalated further, with new tariffs and import restrictions on both sides adding to the uncertainty facing Canadian businesses and the broader economy.
Against this backdrop, several key positions made significant progress during the month, and a handful of holdings contributed meaningfully to returns. That reinforces our focus on company-specific catalysts, sound balance sheets, and attractive valuations: opportunities where value creation does not depend on a broader market recovery.
Mise à jour sur le Fonds
Greenfire Resources Ltd. (GFR) - was a top contributor in September. We increased our position through the rights offering completed during the month, subscribing for our full entitlement and requesting the maximum additional allotment at C$6.74/sh, a material discount to the prevailing market price. The proceeds were used to repay acquisition-related debt and strengthen the balance sheet. We believe that Greenfire’s long-life oil sands assets offer meaningful cash-flow leverage to oil prices and see additional upside from production growth and improved operating efficiency. In our view, the shares remain dislocated relative to the underlying asset base and longer-term cash-flow potential, offering an attractive combination of company-specific catalysts and commodity exposure.
Sangoma Technologies Corp. (STC) - one of the Fund’s largest positions, announced in September an agreement to be acquired by BRC Group Holdings at an implied premium of around 47% to its pre-announcement TSX closing price. In our view, this transaction highlights the opportunity in undervalued small- and mid-cap companies, where strategic buyers can recognize value that public-market prices do not reflect. We see a supportive M&A backdrop across our core investable universe as buyers pursue scale and synergies. We believe several other holdings combine compelling valuations, strategic appeal and identifiable catalysts, although the timing and likelihood of any transaction remain uncertain.
5N Plus Inc. (VNP) - We added to our position in 5N Plus after a significant compression in its valuation multiple from earlier highs, despite continued operating momentum, a substantial backlog and a healthy balance sheet. The company was selected for a US government award to develop domestic gallium arsenide electro-optical components, with Lockheed Martin as the initial qualification customer, which could create a potentially important growth opportunity. In our view, the strategic significance goes beyond the award itself: successful qualification could establish another business with high barriers to entry serving defence and space markets. We see the valuation reset as an attractive opportunity to increase exposure to the company’s space solar and renewable energy businesses, with further upside from emerging critical-material applications.
Titres perdants during September included critical minerals holdings such as Blue Moon Metals Inc. (MOON), as well as our US cannabis positions, which fell after anticipated recreational legalization was delayed. Base metals and gold producers also weighed on returns as lower commodity prices pressured their shares. Uranium producers sold off despite rising uranium prices, a disconnect between the commodity and the equities. Across these holdings, we remain focused on separating sector-driven volatility from developments that materially change the investment thesis, with particular attention to balance sheet strength and company-specific catalysts.
Mises à jour sur le portefeuille
Volatility continued into the fall, with meaningful dispersion across sectors and individual names. Given a number of unresolved risks, and a market that in our view has priced in a fair amount of good news, we believe a measured, defensive approach remains warranted. We have positioned the portfolio around three priorities:
- Préserver les options :: Against this backdrop, we continue to maintain a defensive posture with a cash position. This was not intended as a broad market call; rather, the additional liquidity provides the Fund with greater flexibility to capitalize on forced selling and company-specific dislocations without having to reduce core positions at an inopportune time.
- Augmenter l’exposition aux catalyseurs majeurs: We increased exposure to investments with identifiable, time-bound catalysts—such as contract awards, recapitalizations and strategic transactions—where returns are more dependent on company-specific developments than on broad market direction or multiple expansion. We believe these opportunities can provide a more differentiated source of return when market beta becomes less reliable.
- Maintenir la protection contre les baisses: We maintained portfolio hedges to moderate downside participation while preserving exposure to our highest-conviction investments. With headline index stability masking meaningful dispersion and several macroeconomic and geopolitical risks still unresolved, we believe maintaining protection is prudent and should leave the Fund well positioned to deploy capital if volatility creates more attractive opportunities.
Amar Pandya, CFA
Gestionnaire de portefeuille
October 21, 2026
1 Tous les rendements signalés sont ceux des parts de catégorie F du Fonds. D’autres catégories de parts sont offertes. Celles-ci pourraient présenter des frais et des rendements différents. Les données standards sur le rendement du Fonds sont présentées ici : https://penderfund.com/fr/fund/pender-alternative-special-situations-fund/
Les données standards sur le rendement des fonds alternatifs liquides de Pender sont présentées ici : https://www.penderfund.com/fr/
Ce commentaire comporte un Avis de non-responsabilité, que vous pouvez consulter ici : https://www.penderfund.com/fr/disclaimer/
© Copyright Gestion de capital PenderFund ltée. Tous droits réservés, octobre 2026.