September was another challenging month for global equity markets. Concerns about inflation, alongside ongoing tensions in the Middle East, weighed on sentiment. US Treasury yields rose to multi-year highs across the curve, and the 30-year yield reached its highest level since 2002. The Pender Global Small/Mid Cap Equity Fund returned -4.9% in September, compared with -1.4% for the MSCI World SMID Cap Gross Total Return USD Index (CAD).
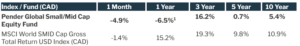
Portfolio weights are 46.8% US equities, 35.1% Canadian equities and 16.1% international equities.
Interest rate expectations and policy kept shifting through the month. Most notably, the US Federal Reserve (Fed), the European Central Bank (ECB) and the Bank of Japan all raised rates in September. The Bank of Canada and the Bank of England held steady. Large-cap technology stocks again outperformed, and the divergence between sectors and market caps remained a defining feature of global markets. The gap showed most clearly in broader indices and small caps, which came under selling pressure as long-term bond yields climbed to multi-decade highs.
The Russell 2000 fell 5.3%, its largest monthly decline in 18 months, as investors priced in higher borrowing costs for longer. Even so, in our view, the global economy continued to perform well. September flash composite purchasing managers’ indices (PMIs) rose to their highest levels since mid- 2021 in the US and since early 2023 in the euro area. The US remained the main engine of developed-market growth, helped by strong business investment, capital spending on artificial intelligence (AI) and a better labour market. Consumer spending also held up, partly because households drew on savings as real personal income growth stalled.
As sector divergence becomes more extreme, the gap between where capital is flowing and where value sits keep widening. We remain excited about the investment prospects we’re seeing globally, where quality small and mid-cap businesses continue to trade at valuations we find compelling. We believe this kind of environment rewards active, bottom-up stock selection.
Fund Specific Updates (September)
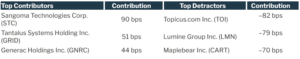
Sangoma was the top contributor after it announced that BRC Holdings, a diversified holding company, will acquire it. The deal values Sangoma at an enterprise value of about US$204 million (C$289 million). That is a premium of about 47% to the closing price the day before the announcement and about 51% to the 10-day VWAP. The transaction is expected to close no later than early 2027.
Generac was another top performer after it announced a long-term agreement to supply backup generators for Amazon’s data centres. Initial deliveries under the agreement are expected to total about US$2.4 billion across 2027 and 2028. As part of the deal, Generac issued Amazon a warrant to buy up to about 1.7 million shares at an exercise price of US$200.93. We believe the agreement gives better visibility into Generac’s data centre revenue and profit opportunity over the next two years and beyond.
Tantalus also performed well after it was added to the Nasdaq OMX Clean Edge Smart Grid Infrastructure Index (QGRD). It was one of seven companies added in the index’s semi-annual reconstitution. As a result, Tantalus is now held by the First Trust Nasdaq Clean Edge Smart Grid Infrastructure Index Fund (GRID), an ETF with about US$12.1 billion in net assets. Management noted that the inclusion raises the company’s profile with investors focused on electrification, energy infrastructure and grid modernization.
Topicus et Lumine, both part of the Constellation Software ecosystem, were the Fund’s top detractors in September. In our view, the weakness appears to reflect both multiple compression across the software sector and company-specific news. Investors are still working out what AI could mean for traditional software business models, and that uncertainty has pressured valuations across the sector.
For Topicus, the biggest news was that longtime CEO Robin van Poelje would retire effective October 1, 2026, and stay on as Chairman. Ramon Zanders was named his successor. Alongside the leadership change, Topicus announced plans to further decentralize its operating groups. The changes are meant to strengthen the company’s operating model, but the transition added some uncertainty about future execution and capital allocation.
We believe Lumine’s weakness seemed tied more to sector sentiment than to any negative company news. On September 28, its subsidiary Incognito Software Systems launched NEXA, an AI-driven network intelligence platform. The launch shows that Lumine’s businesses are building AI into their products, and that the technology brings opportunity as well as the risk of disruption.
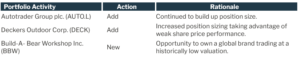
Build-A-Bear Workshop is a new position in the portfolio. As retail is increasingly “Amazon-ed” and experiences “AI-ed,” we believe that Build-A-Bear has set itself apart by turning a commoditized product into an experience that is hard to replicate online. The market still sees a niche mall-based toy retailer, but we see a high-return, cash-generative brand with structurally improved margins and growing asset-light commercial and international businesses. The customer base is also more diversified than many assume: birthday-related purchases make up about 30% of sales, and teens and adults account for roughly 40%.
We used share price weakness after a disappointing second quarter to build our position. Softer US traffic, merchandising missteps and slower commercial expansion led management to lower full-year revenue guidance to US$500–525 million. Near-term execution remains a concern, but we believe the market is mistaking temporary weakness for structural decline. We see an attractive valuation for a differentiated experiential brand with several avenues for growth.
Équipe des actions à petite capitalisation Pender
October 16, 2026
1 Tous les rendements signalés sont ceux des parts de catégorie F du Fonds. D’autres catégories de parts sont offertes. Celles-ci pourraient présenter des frais et des rendements différents. Les données standards sur le rendement du Fonds sont présentées ici : https://penderfund.com/fr/fund/pender-global-small-mid-cap-equity-fund/
Les données standards sur le rendement des fonds alternatifs liquides de Pender sont présentées ici : https://www.penderfund.com/fr/
Ce commentaire comporte un Avis de non-responsabilité, que vous pouvez consulter ici : https://www.penderfund.com/fr/disclaimer/
© Copyright Gestion de capital PenderFund ltée. Tous droits réservés, octobre 2026.