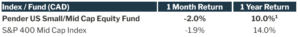
In September, one theme was difficult to ignore: the growing divergence between the areas of the market driving returns and those being left behind. Dispersion has been a recurring feature of 2026, but it became particularly pronounced heading into the fall. For the month, the Pender US Small/Mid Cap Equity Fund declined 2.0%, roughly in line with the 1.9% decline in the S&P MidCap 400 Index, in Canadian-dollar terms. Over the past year, the Fund returned 10.0%, compared with 14.0% for the benchmark.
Looking beneath the headline returns helps explain the gap. A meaningful share of the benchmark’s performance this year has come from areas where we have deliberately held less exposure including negative to low return on capital (GAAP) Information Technology companies. Their current profitability remains modest relative to their valuations and share prices have been supported less by earnings than by enthusiasm around AI and, increasingly, cybersecurity.
The cybersecurity rally shows how quickly sentiment can move in these areas. In April, Anthropic unveiled its Mythos model, and its advanced cyber capabilities raised new concerns about how AI could be used to find and exploit vulnerabilities. Investors responded by bidding up companies positioned to benefit from higher security spending. Those concerns have only intensified since. In early October, JPMorgan Chase CEO Jamie Dimon said that risks from AI “went up 10-fold after Mythos.” For investors, in our view, that has reinforced expectations of sustained investment in cyber defence, even where valuations already reflect much of that optimism.
None of this means we are negative on AI. We continue to see the buildout as a significant investment cycle. Our preference, however, remains the “picks and shovels” businesses that supply the infrastructure it requires, such as power, cooling, connectivity and other critical components. In these areas we believe there is durable demand alongside attractive returns on capital and strong cash generation.
Part of our caution on higher-valuation technology companies comes down to how their earnings are measured. To reflect this, we have a screen in our investment process to exclude companies where stock-based compensation exceeds 10% of revenue. Stock-based compensation is a non-cash expense when it is recognized, but it is a real economic cost to shareholders through dilution. At elevated levels, companies must spend significant cash on share repurchases simply to offset the dilution from vesting equity awards. We are therefore wary of non-GAAP earnings multiples that exclude stock-based compensation, particularly when it makes up a meaningful portion of adjusted earnings. Ultimately, we believe valuation should reflect the true economic cost of running a business and the cash flows available to shareholders.
Periods like now are a useful reminder of what we are, and are not, trying to do. We remain focused on owning quality businesses with strong cash flows, attractive returns on capital and capable management teams, at valuations that we believe provide an appropriate margin of safety. This discipline can lag at times, when the market is rewarding rapidly rising valuations or the latest investment theme. We do not believe the right response is to abandon the framework. Instead, we remain patient and focused on finding businesses where fundamental value creation can drive returns over the long term.
Additional Fund Updates
Generac Holdings Inc. (GNRC)- Announced a long-term agreement with Amazon to supply backup generators for Amazon’s data centers. Initial deliveries are expected to total US$2.4 billion across 2027 and 2028. Generac issued Amazon a warrant to acquire up to ~1.7 million shares at an exercise price of ~US$200.93, exercisable through September 2033. We believe the agreement improves visibility into Generac’s data center revenue and profit opportunity over the next two years and beyond.
Fluor Corp. (FLR) together with its joint venture partner JGC Corporation, was awarded the engineering, procurement and construction (EPC) contract for Phase 2 of the LNG Canada export facility in Kitimat, B.C. Fluor will book its US$7.5 billion share of the ~US$15 billion contract in Q3 2026. Phase 2 will add two liquefaction units and an additional LNG storage tank, roughly doubling the facility’s capacity to approximately 28 million tonnes per annum.
Jabil Inc. (JBL) reported stronger-than-expected Q4 FY26 results in September. Revenue was US$10.6 billion, up 29% year over year, more than US$1 billion above the midpoint of its outlook in June. AI-related demand continued to accelerate, and new capacity came online sooner than expected. FY27 guidance also came in ahead of expectations, with AI-related revenue expected to grow 54% year over year. Jabil’s asset-light model and its mix shift toward the higher-margin Intelligent Infrastructure segment have helped lift core ROIC from roughly 20% in FY20 to 59% in FY26.
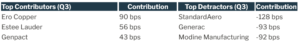
Ero Copper Corp. (ERO) - was a top performer in the quarter after reaching a significant financial and operational inflection point. The company is moving from a heavy capital investment phase into a period of production growth and deleveraging. In September, Ero hosted a capital markets day in São Paulo highlighting progress across its operations, which helped raise its visibility with investors. We continue to like copper as a way to invest in both the infrastructure build-out and the energy transition, particularly as years of underinvestment in new supply meet rising demand centres.
Estée Lauder Companies Inc. (EL) – was another top performer as the company continues to make meaningful progress on its turnaround. Sales growth is improving, profitability is stronger and there are encouraging signs of recovery in China. Importantly, the company’s most recent earnings release showed its “Beauty Reimagined” strategy beginning to translate into better financial results.
StandardAero Inc. (SARO) stock came under pressure from the continued rise in the price of Jet Fuel on the expectation that demand for air travel will come under pressure due to inflation in ticket prices. However, management has indicated that its capacity is fully booked for 2026 and 2027. They are not seeing any change in demand as historically it takes a sustained rise in costs for over 12 months for airlines to reduce flights as the initial curtailment in demand is absorbed by lower utilization.
Aman Budhwar, CFA
October 16, 2026
1 All Pender performance data points are for Class F of the Fund. Other classes are available. Fees and performance may differ in those other classes. Standard Performance Information for the Fund may be found here: https://penderfund.com/fund/pender-us-small-mid-cap-equity-fund/
Standard Performance Information for Pender’s Fixed Equity Funds may be found here: https://www.penderfund.com
This commentary is subject to the Disclaimer found here: https://www.penderfund.com/disclaimer/
© Copyright PenderFund Capital Management Ltd. All rights reserved. October 2026.