In September, the Pender Small Cap Opportunities Fund returned 0.1%¹, outperforming the Russell 2000 Index, which declined 2.7%, and the Russell Microcap Index, which fell -1.6%. Small-cap equities faced a challenging backdrop during the month, as elevated interest rates, higher borrowing costs and continued market concentration in large-cap technology weighed on relative performance.
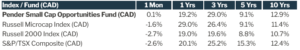
Portfolio weights ~77.8% in Canadian equities and ~17.9% in US equities.
Despite ongoing volatility, we remain constructive on the opportunities emerging across the small-cap universe. One theme we are following closely is the return of the physical economy, meaning a renewed cycle of investment in the infrastructure, energy systems and natural resources that global growth depends on. In our view, several forces are converging to drive this cycle: artificial intelligence, electrification, reshoring, defence spending and energy security. The previous cycle was built largely on software and asset-light business models. Today, the industries driving growth require heavy investment in physical assets, from electricity generation and transmission to mining, pipelines and industrial infrastructure.
While there are parallels with past commodity cycles, there are also important differences. The last supercycle was driven mainly by China’s industrialization and rapid demand growth. This one may be shaped more by supply constraints, geopolitical fragmentation and years of underinvestment. Rising electricity demand from AI and data centres, along with efforts to secure domestic supply chains, is adding new demand at a time when permitting timelines are long and new capacity is limited.
We believe Canada is particularly well positioned. It has abundant natural resources alongside deep expertise in energy and resource development. In our view, the policy environment is also shifting, with renewed focus on permitting reform, major infrastructure projects and attracting investment. Execution challenges remain, but these developments could help turn Canada’s resource advantages into real economic opportunities.
Importantly, this opportunity also goes beyond extraction. By expanding domestic processing, strengthening electricity infrastructure and attracting energy-intensive industries, Canada could capture more of the value from its natural resources. Still, the need for infrastructure does not automatically produce attractive returns. Project economics, capital discipline and valuation remain critical.
Looking ahead, we remain cautious on broader market conditions and we have kept a more defensive posture so that we have flexibility to act as opportunities arise. We believe the infrastructure investment needed over the next decade could create compelling long-term opportunities across several sectors, even while near-term uncertainty weighs on equity markets. We also continue to remain high conviction on software, where we continue to find high-quality businesses at attractive valuations. Our approach is unchanged. We look for undervalued small-cap companies with strong economics, capable management teams and compelling long-term prospects. We remain patient and disciplined, ready to use market volatility to buy quality businesses at attractive prices or add to existing high conviction holdings.
Portfolio Holdings – Updates
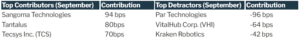
Sangoma Technologies Corp. (STC) was the top contributor after announcing it will be acquired by BRC Holdings, a diversified holding company. The transaction values Sangoma at an enterprise value of approximately US$204 million (C$289 million). That is a premium of about 47% to the closing price on the day before the announcement and about 51% to the 10-day VWAP. We see the deal as evidence of two things: how undervalued technology remains at the smaller end of the market, and how active the M&A environment currently is. The transaction is expected to close no later than early 2027.
Tantalus Systems Holding Inc. (GRID) also performed well after being added to the Nasdaq OMX Clean Edge Smart Grid Infrastructure Index (QGRD). It was one of seven companies added in the index’s semi-annual reconstitution, effective before market open on September 21, 2026. As a result, Tantalus is now held by the First Trust Nasdaq Clean Edge Smart Grid Infrastructure Index Fund (GRID), an ETF with approximately US$12.1 billion in net assets. Management noted that the inclusion broadens the company’s visibility among investors focused on electrification, energy infrastructure and grid modernization.
PAR Technologies Corp. (PAR) was the largest detractor, as investors continued to reassess valuations and profitability for smaller, growth-oriented software companies. We view the selloff as driven by valuation and sentiment rather than fundamentals. During the month, Kwik Fill selected PAR as a long-term strategic technology partner. Kwik Fill will use PAR Retail’s platform and PAR Intelligence to deliver more personalized customer experiences and to support its modern retail strategy.
Kraken Robotics Inc. (PNG) also declined during September as investors continued to assess the company’s recent acquisition of Covelya. Large acquisitions can introduce meaningful integration and execution risks, and both the market and our team are closely monitoring the company’s progress. Investors appear to be awaiting greater evidence of earnings growth and successful integration.
Pender Small Cap Opportunities Fund Team
October 15, 2026
¹ All Pender performance data points are for Class F of the Fund. Other classes are available. Fees and performance may differ in those other classes. Standard Performance Information for the Fund may be found here: https://www.penderfund.com/fund/pender-small-cap-opportunities-fund/
Standard Performance Information for Pender’s Equity Funds may be found here: https://www.penderfund.com
This commentary is subject to the Disclaimer found here: https://www.penderfund.com/disclaimer/
© Copyright PenderFund Capital Management Ltd. All rights reserved. October 2026.